Showing posts with label Unitedhealth. Show all posts

Wednesday, February 19, 2014

Are Drug Letters Harming Our Patients?

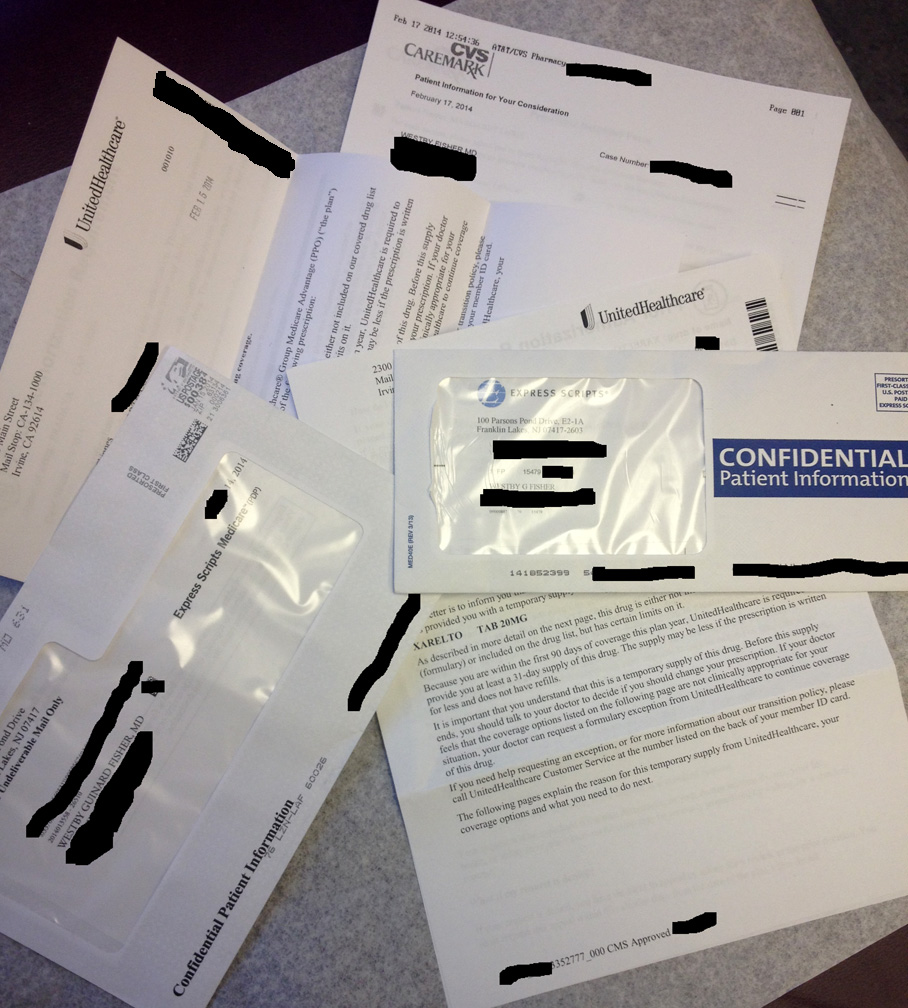
One week's worth of drug letters
Now that a new year has come and gone, I have been swamped with letters from pharmacy benefit manager and insurance companies.  Piles of them.  Not only do these letters consume hours of time each week to address (so much for the "efficiency" of the electronic medical record), I am worried some of the latest practices of these companies might be endangering my patients. 

Here's a typical (paraphrased) letter that has me most concerned:
"Dear Mr or Ms Patient:

This letter is to inform you that Insurance Plan XYZ ("the plan") has provided you with a temporary supply of the following prescription:

(Insert your favorite novel oral anticoagulant name/dose here)

As described in more detail on the following page, this drug is either not included on our covered drug list (formulary) or included on the drug list, but has certain limits on it.

Because you are within the first 90 days of coverage this plan year, TooBig Insurance Company is required to provide you with at least a 31-day supply of this drug.  The supply is less if the prescription is written for less and does not have refills...

It is important you understand this is a temporary supply of this drug.  Before this supply ends, you should talk with your doctor to decide if you should change your prescription.  (Emphasis mine) If your doctor feels that the coverage options listed on the following page are not clinically appropriate for your situation, your doctor can request a formulary exception from TooBig Insurance Company to continue coverage of this drug.

If you need help requesting an exception, please call TooBig Insurance Company Customer Service listed on the back of your member ID card."
Note that all novel oral anticoagulant medications carry a very specific black-box warning from the FDA regarding discontinuation of these medications. Here's the black box warning for rivaroxaban (Xarelto):
"A. PREMATURE DISCONTINUATION OF XARELTO® INCREASES THE RISK OF THROMBOTIC EVENTS

Premature discontinuation of any oral anticoagulant, including XARELTO®, increases the risk of thrombotic events. If anticoagulation with XARELTO® is discontinued for a reason other than pathological bleeding or completion of a course of therapy, consider coverage with another anticoagulant.
"
Should insurance companies be allowed to restrict the dispensing of any medication where doing so puts patients at risk of injury?  Why are insurance companies allowed to potentially violate FDA-mandated black box warnings if they do so?   How many lives are being placed at risk by this practice?  What about the patients that are blind or can't read?  What happens to them? 

On a more selfish note: why must the physician suffer the liability consequences of an insurer's profit-driven  actions that disregards the safety and well-being of our patients? 

Why?

-Wes


Friday, June 12, 2009

Pajamas Medicine

Wow, online consultations for $25 every 10 minutes! Compudocs for $150/hour.

Not bad, I guess, and it's the new rage with insurers. But "compudoc" sounds so boring. I want to coin a new name. Call it "pajamas medicine." After all, PJ medicine can be performed from the comfort of your own living room, any time of the day or night.

So here's a question: why not open pajamas medicine up to the rest of the world? I mean, think of where those prices might go! Maybe we'll be working for under $20 and hour soon! Wooooo hooooo! No fuss, no mess. No chance for the spread of swine flu because you don't even have to touch a patient!

And liability coverage? Well, that might be a little sticky...

But hey, let's not ask the tough questions. After all, it's medicine as a commodity coming to a computer terminal near you.

Oh, and that sentinal node? I'm sure it'll be the first thing they tell you about online.

Really.

-Wes

h/t BNET Healthcare.

Wednesday, December 03, 2008

Continuing Continuous Continuity

Insurance for insurance: just what the economy and perverted health care system ordered:
Called UnitedHealth Continuity, the product is not actual medical insurance, but is aimed at people who may have insurance now but are worried they may lose it — and may not be able to obtain replacement insurance on their own. They may expect to retire early, for example, before they qualify for Medicare. Or they are worried about the possibility of losing their job and their health coverage.

People who are already sick will generally not be eligible for the new product. Those who do pass a medical review, will pay 20 percent each month of the current premium on an individual policy to reserve the right to be insured under the plan at some point in the future.

“What this product is designed to do, for a very modest premium, is to essentially protect your insurability for the future,” said Richard A. Collins, the president of UnitedHealth’s individual insurance unit, who says he is the first policy holder. His monthly fee is $50.
Who says these guys aren't thinking ahead?

Now, just so they don't think doctors aren't one up on the insurers, I'd like to introduce "Dr Wes's Continuous Continuity Continuation Insurance," guaranteed to be sure you can get other Continuity insurance from any and all other insurance vendors sure to hop on the insurance-on-insurance bandwagon. It is available for nominal premium of $1 a month, payable directly to my bank account and conveniently payable through PayPal. (Why should I be left out of the fun and games?)

These financial guys are something, aren't they? Its another product similar to the derivatives market for the housing industry, no?

Brilliant.

-Wes

Monday, December 01, 2008

A Portal to NoWhere

Boy, not only will insurers take your money to "spread the wealth" of risk for healthcare, they're now into web portal design and maintenance! I mean, I want insurers to tell me about sweet potato soup recipes, don't you? It's such an efficient use of our health care dollar, right?

And don't get me started about their helpful symptom checker, designed specifically to delay a call to a health care professional that would take a fraction of the time to deal with a patient's concerns. Oh no, we can all be reassured that diagnoses made here are MUCH more accurate as the poor patient is dragged through this an algorithm-driven, inflexible system. We've seen how good others were at this approach. I mean, why talk to a person?

I find this development concerning. First, to suggest that "wellness" is going to reduce health care costs is contradicted here. Is this not just another attempt to market for services? How much does this marketing camppaign cost the patient already burdened with ever-higher insurance premiums? Where, exactly, are the cost savings in sweet potato soup recipes? Are people really saving money as they are directed to yet another website in the interest of becoming "AlphaWell?"

And where else might this disgusting display of waste take us?

I'd say, to the cleaners.

-Wes

h/t: WSJ (subscription).

Friday, December 07, 2007

0.5 percent

...that's what Mr. William McGuire's fine to the SEC was for his stock option backdating scandal relative to the estimated value of those stock options (estimated to be worth $1.4 billion dollars).

Poor Mr. Mcguire. He also had to "forfeit" (mind you, he never was "paid" anything, but rather had an "option," potentially, to cash in on the money) $620 million back to Unitedhealth's board in an agreement not to be sued by their shareholders.

And he gets to "exercise" (i.e., get paid) $800 million because he was such a nice guy as to give up 43.7% of his potential haul.

PLUS, he spends no time in jail.

I hope this isn't too tough on him. I mean, after all, he was such a nice guy to so many peoples' portfolios.

But patients ultimately paid the price for this mess, you know: through denied claims and by having to change doctors as health care "plans" were reorganized to assure Unitedhealth's profits as they gobbled up competitors through shrewd business practices that obfuscated and delayed payments to physicians and their patients.

This, my friends, is the real healthcare crisis story in a nutshell. Sugar-coating healthcare as "wellness" in hopes of stealing from the poor to feed the rich, all in the name of profitting investors.

Now in the time of our election, we must look for change, but there's one small problem:
Traditionally, the financial sector — banks, insurance companies, and the real estate industry — has been the largest source of funds for presidential and congressional races, followed by lawyers and lobbyists and then ideological and single-issue groups, according to the Center for Responsive Politics.
So do we think things will change substantially?

Of course not.

After all, the government is still gloating over their 0.5 percent fine to Mr. Mcguire.

-Wes

0800 AM CST Addendum: My original post claimed it was 0.000005% earlier this AM - I had not had my coffee yet. The correct percentage amount was calculated as: $7,000,000 / $1,400,000,000 x 100% = 0.5% for Mr. Mcguire's fine paid to the SEC. I regret my earlier miscalculation.

Friday, September 07, 2007

Unitedhealth Gets Off Easy

I was going to comment on the ridiculously small sum ($20 million) UnitedHealth will have to pay the 36 states as part of a settlement to resolve problems with the insurer's claims-paying systems. Fortunately, Dr. Rich Fogaros over at The Covert Rationing Blog nails it on the head:
First, the insurance companies themselves are the only entities that fully understand their labyrinthine reimbursement schemes; they control the process. In this light it is telling that UnitedHealth Group and the regulators have been “negotiating” the “improved” reimbursement procedures for at least a couple of years. In a culture swimming in seamless electronic processing systems, the puzzle of simplifying claims processing should have been solvable in a couple of weeks.

Second, remember that the Wonkonians themselves, in the guise of Medicare and Medicaid, are also deeply engaged in purposefully mysterious reimbursement schemes. One suspects that there’s a limit to how far they’ll push the insurers toward transparency and simplicity, lest the expectation for similar processes is turned back on them.

Third, when was the last time any regulators have ever been able to simplify anything?
And when one figures that $6 million of that payout will go to New York alone (for their time and effort, I guess) and divides up the rest evenly among 35 states, we see that the other states get paid, on average, a little over $570,000 each.

Now compare that the top 25 CEO pay amounts (salary, bonus, exercised options and vested stock grants) for 2005 (the year the original suit was filed). We see that all twenty-five received over $35 million EACH in a single year.

Sorry, but when UnitedHealthcare CEO Kenneth Burdick says: “This new, forward-thinking approach focuses the regulatory process for the states and our company on a practical set of uniform performance standards, while providing clearer and more meaningful means of assessing how well we are serving customers.”

We get, it Ken. Crystal.

You won.

Guess we can look for those premiums to rise again next year to cover the cost of these "uniform performance standards," eh?

-Wes

Friday, July 20, 2007

Cigar Smokers Are Fumed

Tax Mike Ditka's cigars to support health care for more needy children? Sounds nice like a plan.

But what happens when the government wants to provide more health care to uninsured or underinsured adults, too? Who or what will be taxed then?

Meanwhile, the third-party medical juggernaut continues with UnitedHealth's net profits soaring.

-Wes

Saturday, May 05, 2007

On Lizards: Legal and Far From Laudible

Illinois is proposing to tax businesses making over $2 million a year (who will pass this expense on to consumers) to support a sweeping health care and education funding plan. The 0.08-1.95% tax (called the Gross Receipts Tax or GRT) is in addition to our already high 8% sales tax. Businesses, understandably, are outraged. That is, everyone except businesses in the food industry and medical industries, which are exempt.

I wonder if the health insurance and pharmaeutical industries consider themselves "medical" industries?

But his question is a mute one, I suppose, because most of the Lizards in these industries are based outside our state anyway. UnitedHealth, the largest health care insurer in America for instance, is based in Minneapolis, MN and has been noted to practice many slithering techniques. Blue Cross and Blue Shield, Aetna and Cigna have been similarly implicated in slimy behaviours.

Remarkably, it seems likely that the health insurance industry and pharmaceutical industries will have to contribute nothing to the control of health care costs in our state while enjoying few restrictions to raising costs.

Why is this a problem? Because not only does small business have to get taxed more based on the Illinois plan, they also have to endure the threat of retribution of insurers like what UnitedHealth did to one small business in Ohio:
Despite the 40 percent ceiling (on annual health care premium rate increases) in Ohio, for instance, United Healthcare early this year levied an increase of more than 100 percent on the premiums of CBG Biotech, a 26-employee hospital supplies maker in Macedonia, near Akron. The insurer argued that the high increase was justified because CBG had violated its contract.

Ohio permits insurers to solicit advance medical information from employees. One CBG worker had failed to disclose his wife’s multiple illnesses — including cirrhosis, gout and an ulcer — when he signed up for coverage, according to a letter from United that became part of a court record.

When United learned of the omission after the woman was admitted to a hospital, where she died, “they decided to punish the entire company,” said CBG’s chairman, Gerald W. Camiener.

United raised CBG’s total premium for the duration of the contract to $18,000 a month, from $8,800, he said, and demanded $118,000 in back payments.

CBG sought a federal injunction against the increase. In February, Judge Ann Aldrich of the United States District Court in Cleveland denied the CBG request, saying that United Healthcare’s actions were permissible under its contract and “very likely legal, but also very far from laudable.”

Mr. Camiener, in an e-mail message, lamented that ruling. “In the past, the policy of health insurers was to disqualify the employee when wrong information was furnished to them,” he wrote.

“Now,” he continued, “the insurers will be coming to the employer and demanding exorbitant sums of money with the threat that the entire group will be cut off forthwith, even in the middle of a policy year.” Mr. Camiener changed his company’s health coverage to Aetna, paying about $15,400 a month in premiums, and he complained to senior executives at United.
If we think for even one moment that these practices couldn't happen here in Illinois, we're deluding ourselves. And it will be legal, but far from laudible indeed that the insurance industry won't have to contribute a dime to the health care costs in our state. Meanwhile, we've had to suck up another tax to feed those greedy lizards that prey on small business.

-Wes

Photo credit.

Tuesday, April 10, 2007

UnitedHealth's Self-Referral

The line has been crossed. UnitedHealth, the health largest insurance provider in America, not only has officially decided who, when and where patients should get care, they've decided that if physician's don't comply, they'll be fined and removed from their network, forcing patients to switch providers:
(WSJ) Most health plans are designed so their members pay more when they go to an out-of-network doctor or take a nonpreferred medication. But the financial sanctions -- which UnitedHealth has yet to impose -- mark the first time a physician could be fined by a health insurer if he or she directs a patient to seek out-of-network care or testing, the American Medical Association says.

The threats stem from a 10-year deal that UnitedHealth struck late last year with Laboratory Corp. of America Holdings to become its national in-network laboratory. With 28.5 million health-plan members and growing, UnitedHealth has been using its heft more and more in recent years to negotiate cut-rate fees with doctors, drug makers and other suppliers. In the same vein, it signed on Lab Corp. after its longtime lab partner, Quest Diagnostics Inc., said it couldn't accept new terms that UnitedHealth wanted and dropped out of contract negotiations.

To squeeze as much savings as possible out of the Lab Corp. deal, UnitedHealth sent a not-so-friendly reminder to doctors to play along. If doctors consistently failed to refer patients to Lab Corp. or other local in-network lab facilities as of March 1, UnitedHealth said it reserved the right to fine them $50, cut their fees or oust them from the network.
Is this where we're going to cut health care costs in America? Fine the doctor. As if we set the lab prices. Is the monopolization and WalMart-ization of health care always in the patient's best interest? Or could there just be, in the interest of corporate profits, an ulterior motive? I can just see UnitedHealth's Directors and Board Members sitting around the board room table:
Hey Donna! I gotta idea how the heck we can pay for ol' McGuire's accountant fees and post-retirement corporate jet! We'll just tack on a fine to those pesky physicians! Imagine. 520,000 of 'em ordering way too many tests, say twenty a day, about five of which we can find as improper, times fifty bucks. Hell, that'd be a cool $130 mil! Yeeeeeee Haaaaaa! That'd pay for his jet with a little left over for us! Whatd'ya think, girl?"

"Oh Steve, I love it when you talk dirty!"
I love the double standard. Physicians can't refer to their labs due to concerns over conflicts of interest due to the Stark laws, but insurers can help themselves and do even one better: threaten physicians if they fail to make such a financially-motivated referral that lines the insurance company's coffers.

Oh, but certain self-interested physicians don't seem to mind, especially those in leadership positions poised to profit:
Not all doctors are upset. The American Academy of Family Physicians wrote a letter of concern to UnitedHealth in February. But it told members that the health insurer had eased its worries after clarifying that it would not punish doctors for patient's decisions and only apply the sanctions in rare cases where a doctor repeatedly defied the policy. "This doesn't look as bad as it originally did," says Bruce Bagley, the academy's medical director for quality and improvement. Dr. Bagley also serves on a physician-advisory committee for UnitedHealth.
I wonder how much they payed Dr. Bagley for his time to sit on their committee?

-Wes

Wednesday, December 20, 2006

A Christmas Card to UnitedHealth

Dear UnitedHealth,

Here's wishing you a very Merry Christmas and Happy Hannukah. May the spirit of Christmas remain in your heart as your profits soar.

Your guiding principles remain a true wonder in this season of frugality in health care. Your incredible ability to forecast another stellar year of profits (14%) amid growing health care costs to employers and patients is stunning. We, your shareholders, are breathing a big sigh of relief, especially amid all of the current buzz regarding the ethical practices (*cough*) that have been transpired with all of the options backdating and accounting oversights this year.
UnitedHealth forecast 2007 net income in a range of $4.7 billion to $4.75 billion on revenue of about $79.5 billion. The company also backed its 2006 profit target, pegged in a range of $4.14 billion to $4.16 billion. These forecasts, UnitedHealth said, are based on expectations for "gains from increasing market share and strong operating margins" across its business units. In addition, the company targeted operating cash flow at about $6 billion to $6.2 billion next year.
We know that doctors really appreciate your "margins" of health care coverage each time their patients open their "Explanation of Benefits" letters and have to pay progressively larger portions of their health care bill on top of their premiums to feed our beast. Thank you.

As the challenges to health care grow, we are thrilled to offer you wishes for a "very prosperous New Year" next year (*cough *). Now that Medicare has agreed to have doctors kick in 1.5% of their earnings to provide best practices data for you to reap higher profits, you should be perfectly situated to have an even better year in 2008. Keep up the good work.

Oh, please tell your Chief Executive Stephen Hemsley to stop calling those little oversights "embarrassing." I mean, your actions speak louder than words. Ho ho ho!

Have a wonderful holiday season!

- Johnny Shareholder

Friday, December 01, 2006

UnitedHealth Shareholders Granted a Reprieve

From the Wall Street Journal this AM:
In an unusual move, a federal judge has temporarily barred ousted UnitedHealth Group Inc. Chief Executive William McGuire from exercising stock options or receiving any retirement pay or other exit benefits while an external, board-appointed committee establishes whether the health insurer has claims against him.

The order, which backs a joint motion by attorneys for several shareholder lawsuits and Dr. McGuire himself, puts on hold any agreement between UnitedHealth and its longtime chief executive over the terms of his departure until those legal questions have been answered. Dr. McGuire agreed to resign in October after an internal report concluded millions of stock options were likely backdated on his watch. He left the company yesterday with negotiations over his retirement package still unresolved.

The injunction is unusual in the annals of executive pay. U.S. District Judge James Rosenbaum of Minnesota handed it down late Wednesday partly at the request of attorneys representing a group of shareholder plaintiffs who have filed lawsuits against UnitedHealth. The complaints argue that the option backdating lined the pockets of Dr. McGuire and other top executives at the expense of the company. "If he were able to reap what we see as ill-begotten gains, we'd be asserting a claim without a remedy," said Karl Cambronne, lead attorney for the group.
No so fast, Dr. McGuire. Let's see what the external committee decides. It is also interesting to note:
Dr. McGuire also supported the plaintiffs' push for an injunction, and his attorneys even drafted the proposed court order, according to one person familiar with the situation said. The departing CEO believes the special litigation committee will vindicate him once "all the evidence is in," this individual said.
Let's see, according to one set of outside reviewers, some would put the odds of Dr. McGuire having timed all those option dates just right was about 200 million to 1? And we're not even talking about those other set of double-issued options, are we?

Good luck, Dr. McGuire.

You're gonna need it.

-Wes